ElectronsX > Robots > Humanoid Robots
Humanoid Robots
Humanoid robots are built in human form to work in places designed for people: warehouses, factories, hospitals, offices and homes. They can use existing doors, tools, vehicles and equipment, so a factory built for human workers does not need retrofitting. That fit with human-scale environments is the main commercial case for humanoids.
A humanoid runs real-time AI inference on board and sends heavier reasoning tasks to the cloud. It handles locomotion, manipulation, perception and language at the same time. Batteries hold only about 2-3 kWh, so compute efficiency matters as much as mechanical efficiency. Compute alone can draw 200-400W during active LLM (large language model) inference, a meaningful share of the total power budget.
Most of the semiconductors in a humanoid are analog, mixed-signal and power devices, not AI compute chips (see Semiconductor Content below).
Leading Humanoid Platforms
| Platform | Developer | Status (2026) | Key Differentiator |
|---|---|---|---|
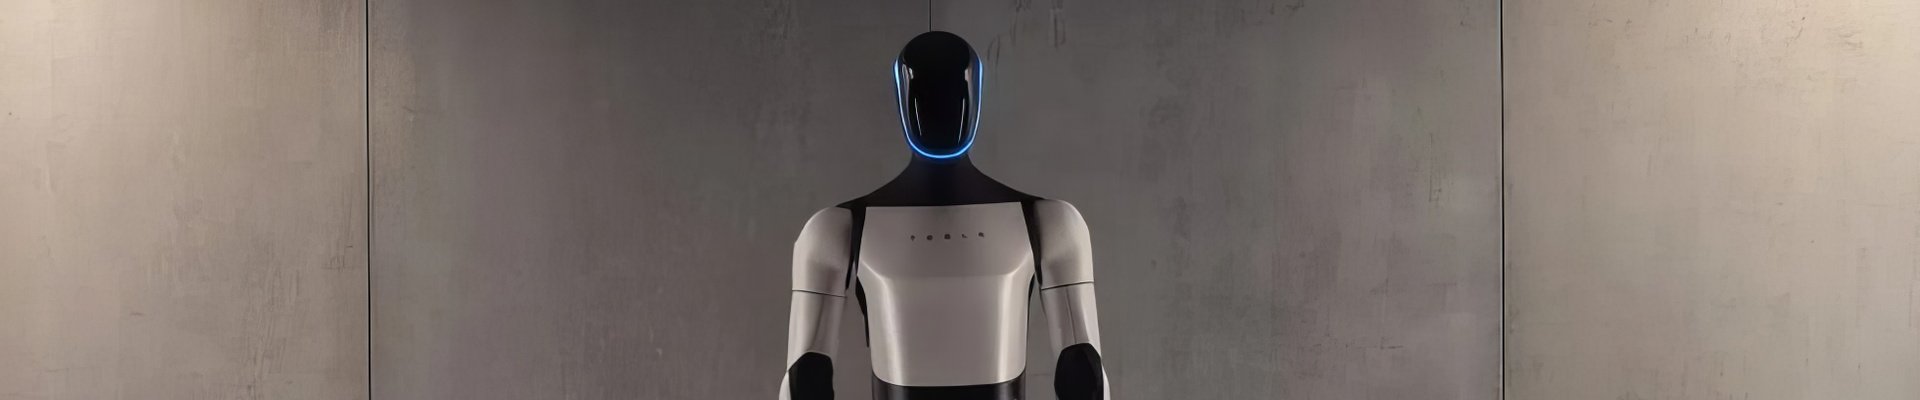
| Optimus Gen 2 | Tesla (US) | Internal deployment | Vertical integration with Tesla EVs |
| Figure 02 | Figure AI (US) | BMW factory pilot | OpenAI partnership; neural control |
| Digit | Agility Robotics (US/Amazon) | Amazon warehouse deployment | Logistics-optimized design |
| Atlas (Electric) | Boston Dynamics (US/Hyundai) | Industrial pilots | Most dynamic locomotion |
| GR-1 / GR-2 | Fourier Intelligence (China) | Commercial sales | Medical and industrial markets |
| H1 / G1 | Unitree Robotics (China) | Commercial sales globally | Cost leadership (~$16K G1 target) |
| Walker S / X | UBTECH (China) | Commercial; automotive factories | Longest commercial track record |
| Apollo | Apptronik (US) | Pilots; Mercedes-Benz partnership | Hot-swappable battery packs |
| NEO Beta | 1X Technologies (Norway/US) | Pilot | Wheeled mobility option |
Platform Notes
- Optimus Gen 2: Internal production deployment, with external commercial availability 2025-2026. The most vertically integrated platform: it shares AI training (Dojo/Cortex), SiC power electronics and battery supply chain with Tesla EVs, and uses custom actuators.
- Figure 02: BMW factory pilot, with commercial scaling 2025-2026. OpenAI partnership for language/reasoning, end-to-end neural control and a rapid iteration cadence.
- Digit: Amazon warehouse deployment at scale; the most commercially deployed Western humanoid. Logistics-optimized design with Amazon integration, proven at commercial scale, and a unique leg architecture.
- Atlas (Electric): Industrial pilots and Hyundai factory deployment. The most dynamic locomotion capability, Hyundai manufacturing integration and a hydraulic-free electric redesign.
- GR-1 / GR-2: Commercial sales with a rehabilitation and industrial focus. Rehabilitation therapy origin, a dual medical/industrial market and an open SDK ecosystem.
- H1 / G1: Commercial sales globally; the lowest-cost full-size humanoid available. Aggressive cost leadership (~$16K G1 target price) and quasi-direct drive actuators mirror the Chinese EV cost-down playbook.
- Walker S / X: Commercial, deployed in FAW/Dongfeng automotive factories. The longest commercial humanoid track record, with automotive factory deployment experience.
- Apollo: Pilot deployments and a Mercedes-Benz partnership. Hot-swappable battery packs enable continuous operation; logistics focus; NASA origin.
- NEO Beta: Pilot with a residential and workplace focus. A wheeled mobility option for energy efficiency; designed for domestic environments.
Hardware Stack
| System | Components | Key Spec |
|---|---|---|
| Powertrain | Li-ion pack (NMC or LFP) | 2-3 kWh; 2-5 hours runtime |
| Actuators | Servo motors, harmonic drives, quasi-direct drive | Harmonic drives a chokepoint |
| Mobility | Bipedal; some wheeled mode | Stairs, uneven terrain |
| Manipulation | Dexterous hands, force-torque sensors | 6-12 DOF hands |
| Perception | Stereo cameras, LiDAR, depth, tactile | Shared with AV sensor stack |
| Compute | Orin/Jetson, GPU, custom AI ASICs | 200-400W during LLM inference |
| Memory & Storage | LPDDR5 RAM; SSD | 16-64 GB RAM; 256 GB-2 TB SSD |
| Networking | Wi-Fi 6/6E, 5G, Ethernet | CAN or EtherCAT internal bus |
| AI & Language | Cloud LLMs; TTS/STT engines | Multi-step task planning |
Hardware Stack Notes
- Powertrain: Lithium-ion battery pack (NMC or LFP); some platforms target solid-state. 2-3 kWh typical, 2-5 hours runtime; hot-swappable on Apptronik Apollo; wireless docking in R&D.
- Actuators: Brushless servo motors, harmonic drives, strain-wave gearboxes, quasi-direct drive, and linear actuators for some joints. Harmonic drives from Harmonic Drive Systems and Nabtesco (Japan) dominate and are a key supply chain chokepoint; Chinese OEMs are scaling rapidly.
- Mobility: Bipedal locomotion for walking, stair climbing and uneven terrain; wheeled mode (1X NEO) improves energy efficiency on flat surfaces.
- Manipulation: Multi-jointed hands, dexterous grippers and force-torque sensors. Dexterous manipulation is the hardest unsolved problem; most platforms have 6-12 DOF hands.
- Perception: Stereo cameras, LiDAR or structured light, depth sensors, and tactile sensors in hands/feet - the same sensor supply chain as the AV stack. IMUs and GNSS for localization; force sensing for safe human collaboration.
- Compute: NVIDIA Orin/Jetson, RTX-class GPU and custom AI ASICs, plus MCU/FPGA motor controllers and safety microcontrollers. 200-400W compute load during active LLM inference; edge inference for latency-critical tasks and cloud offload for reasoning.
- Memory & Storage: 16-64 GB LPDDR5 RAM, 256 GB-2 TB SSD and an edge cache for pre-trained models. Holds local models for offline operation, reinforcement learning policy storage and real-time control loop data.
- Networking: Wi-Fi 6/6E, 5G (private network in industrial deployments) and Ethernet when docked. Internal: CAN, EtherCAT or a custom real-time bus; fleet telemetry and OTA updates via secure cloud link.
- AI & Language: Cloud-connected LLMs (GPT, Gemini or proprietary), TTS/STT engines and multi-modal perception + reasoning. Can plan multi-step tasks, ask clarifying questions and hand off to a cloud LLM; industrial deployments are bounded by safety filters.
Semiconductor Content: Analog & Mixed-Signal, Not AI Compute
Humanoids are often described as AI hardware, with attention on the compute stack: the NVIDIA Orin, the GPU cluster, the LLM inference chip. Most of the semiconductor volume sits elsewhere.
Each humanoid contains an estimated 1,100-2,200 discrete semiconductor devices, of which 400-800 are power semiconductors. They are spread across:
- Joint drives and motor controllers
- Power management ICs
- Sensor interface circuits
- Gate drivers
- Analog signal conditioning
The GaN joint drive inverter is a compact, high-frequency power module that controls each actuated joint. It is the highest-volume device in the humanoid stack and has no direct equivalent in the EV supply chain.
Goldman Sachs projects a $38B humanoid market by 2035. At those volumes, GaN demand from joint drives alone would create a new demand curve that rivals SiC demand from EV traction inverters. Semiconductor suppliers have not yet priced that demand in.
SemiconductorX covers the upstream supply chain in Humanoid Robots - The Analog Semiconductor Story: SiC boule growth, GaN epitaxy, analog/mixed-signal device concentration and the full device count by joint type.
See: Humanoid Actuator Supply Chain | Actuator Power Electronics - GaN Joint Drive Analysis | Humanoid-AV Interoperability - Shared Semiconductors, Shared Autonomy
Deployment & Market Outlook
Humanoids are moving from research prototypes to pre-production deployments in 2026. The first commercial-scale deployments are Tesla, Agility (Amazon), Figure (BMW) and UBTECH (FAW/Dongfeng). All are in factories or logistics sites, where repeated tasks, defined workspaces and safety protocols reduce the autonomy required.
Chinese OEMs are scaling quickly with cost structures modeled on the Chinese EV industry. Unitree's G1, at about $16,000, costs an order of magnitude less than Western equivalents and sets a price floor that will squeeze margins across the sector.
China's humanoid supply chain is also more vertically integrated. It draws on domestic actuator, motor and electronics manufacturing that Western OEMs must build from scratch.
The 2026-2030 shift is from single-task pilots to multi-task deployment in variable, unstructured environments without per-task programming. Progress depends on:
- AI capability: foundation models for robotics
- Actuator reliability: mean time between failures (MTBF) at commercial duty cycles
- Cost: a platform cost under $30,000 for broad commercial deployment
Supply Chain
- Humanoid & Robot Supply Chain - Full Coverage
- Actuator Supply Chain - Harmonic Drives, Gearboxes, Joint Modules
- Actuator Power Electronics - GaN Joint Drives & Motor Controllers
- Humanoid & Quadruped Docking & Charging Infrastructure
- Humanoid-AV Interoperability
Related Coverage
- Autonomous Systems vs. Robots
- Quadruped Robots
- Industrial Robots
- Sidewalk Delivery Bots
- Drones & UAVs
- Autonomous Vehicles & Robots
- Humanoid Semiconductor Deep-Dive (SemiconductorX)
- Humanoid Actuator Supply Chain